Remember me


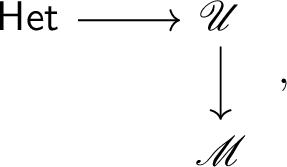

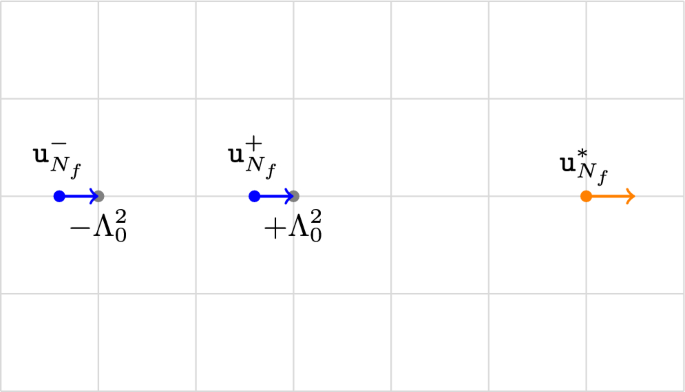

The main goal of this section is to study the trinions obtained through the A- and B-pants decompositions in detail. We then obtain the explicit form of the diagonalization matrices of the linear systems associated to these trinions in terms of the monodromy data, and obtain the expressions for \(\omega _^A\) and \(\omega _^B\), that will be used to compute connection constant \(\Upsilon _S\) in the next section.
3.1 Linear Problem of the Trinion from the A-pants decomposition.In this section we aim to obtain the expression for \(\omega _^A\) starting from the linear system (2.16) on the three-punctured sphere derived through pants decomposition along the A-cycle. First, let us recall the following:
Proposition 1The behaviour of the solution of NAECM model (2.5) \(Q(\tau )\) as \(\tau \rightarrow i\infty \) is given by
$$\begin Q&\sim a\tau +\frac+\frac\log \frac=a\tau +\eta ,\nonumber \\ \quad e^&\frac e^}, \end$$
(3.1)
where \(a,\,\nu \in \mathbb \) are monodromy coordinatesFootnote 3 on the character variety, as in (2.13).
ProofSee [9, Appendix D]. \(\square \)
The local system (2.16) is obtained by studying the behaviour of the Lax matrix at \(\tau \rightarrow i \infty \). The asymptotics of \(x(u,z|\tau )\) reads
$$\begin x(u,z|\tau )\sim \frac-1}-\frac-1}, \end$$
(3.2)
and so, in the same limit, assuming that the monodromy exponent a has small positive real part:
$$\begin L(z)\sim 2\pi i\begin a & -\frac-1}\\ -\frac}-1} & -a \end L_^(z). \end$$
(3.3)
This is the Lax matrix of the three-point problem associated to the A-pants decomposition, which has singularities at \(z\rightarrow \pm i\infty \), and \(z=0\). In order to compute \(\omega _^\) given by (2.21), all we need is to obtain the matrices \(G_^, G_0^\) defined in (2.17), (2.18) that diagonalize the residue matrices of the linear problem above.
Proposition 2The matrices \(G_^, G_^\) read
$$\begin G_^A = \begin e^} & \\ 0 & e^} \end \begin 1 & 0\\ \frac & 1 \end, & G_0^A&= \begin e^ & 0\\ 0 & e^ \end \begin 1 & -1\\ 1 & 1 \end, \end$$
(3.4)
$$\begin G_^A = \begin e^} \frac & 0\\ 0 & e^}\frac \end \begin 1 & \frac\\ 0 & 1 \end, \end$$
(3.5)
which are determined up to left multiplication by constant diagonal matrices parameterized by \(\delta _\), \(\delta _0\), and \(\delta _\), respectively. The parameters \(a, \nu , m\) define the monodromy data as in (2.13).
ProofWe now compute each of the matrices above. Note that the fundamental matrix solution of the linear system
$$\begin \frac^(z)}=Y_^(z)L_^(z) \end$$
(3.6)
with \(L_^(z)\) defined in (3.3) is given by hypergeometric functions:
$$\begin Y_^(z)&= X_0\,(1-e^)^m \begin (-e^)^ & 0\\ 0 & (-e^)^ \end\nonumber \\&\!\times \!\begin }_F_1(m,1+m-2a,1-2a,e^) & \frac}\, }_2F_1(1+m,1+m-2a,2-2a,e^) \\ \frac\, }_F_1(1+m,m+2a,1+2a,e^) & }_2F_1(m,m+2a,2a,e^) \end, \end$$
(3.7)
where \(X_0\) is a normalisation matrix that we will specify below. We now study the asymptotics of the above equation to obtain the matrices \(G_^, G_^, G_0^\) in the following way.
1. Computation of \(G_^\):
To begin with, in the limit \(z\rightarrow -i \infty \), the solution (3.7) has the behaviour
$$\begin \begin Y_^(z\rightarrow -i\infty )&\simeq \widetilde^_(z)= X_0\begin (-e^)^ & 0\\ 0 & (-e^)^ \end \begin 1 & 0 \\ \frac & 1 \end \\& C_^\begin (-e^)^ & 0\\ 0 & (-e^)^ \end G_^A. \end \end$$
(3.8)
The matrices
$$\begin C_^A= X_0 \begin e^} & 0\\ 0 & e^} \end, & G_^A= \begin e^} & \\ 0 & e^} \end \begin 1 & 0\\ \frac & 1 \end, \end$$
(3.9)
are defined up to an ambiguity of left/right multiplication by a diagonal matrix we parameterize by \(\delta _\). Furthermore, the A-cycle monodromy, defined as the analytic continuation \(z\mapsto z+1\), with z in the fundamental region, is
$$\begin Y_^(z+1)&=M_AY_^(z)= X_0\begin e^ & 0\\ 0 & e^ \endX_0^Y_^(z),\nonumber \\ \quad M_A&=X_0\begin e^ & 0\\ 0 & e^ \endX_0^. \end$$
(3.10)
2. Computation of \(G_^\):
To find the B-cycle monodromy we need to analytically continue the hypergeometric function from \(x\rightarrow -0\) to \(x\rightarrow -\infty \), obtained through Kummer’s formula [18, eq. (15.10.25)]
$$\begin }_2F_1(a,b,c,x)&=\frac(-x)^\, }_2F_1(a,a-c+1,a-b+1,x^) \nonumber \\&\quad + \frac(-x)^\, }_2F_1(b,b-c+1,b-a+1,x^). \end$$
(3.11)
The analytic continuation of the fundamental matrix of solutions (3.7) then reads
$$\begin&Y_^(z)=(1-e^)^mX_0 \begin \frac & \frac\\ \frac & \frac \end\nonumber \\&\begin (-e^)^ & 0\\ 0 & (-e^)^ \end \nonumber \\&\times \begin }_2F_1(m,2a+m,2a,e^) & \frac\, }_2F_1(1+m,2a+m,1+2a,e^)\\ \frac}\, }_2F_1(1+m,1-2a+m,2-2a,e^) & }_2F_1(m,1-2a+m,1-2a,e^) \end, \end$$
(3.12)
with leading asymptotics as \(z\rightarrow +i\infty \) given by
$$\begin&Y_^(z)\sim X_0 \begin \frac & \frac\\ \frac & \frac \end \nonumber \\ \times \begin (-e^)^ & 0\\ 0 & (-e^)^ \end \begin 1 & \frac \\ 0 & 1 \end. \end$$
(3.13)
Rewriting the above expression as
$$\begin Y_^(z)&\sim X_0 \begin \frac & \frac\\ \frac & \frac \end \begin e^ & 0\\ 0 & e^ \end \nonumber \\&\quad X_0^ \widetilde_^(z), \end$$
(3.14)
where
$$\begin \widetilde_^(z)X_0 \begin (-e^)^ & 0\\ 0 & (-e^)^ \end \begin e^ & 0\\ 0 & e^ \end \begin 1 & \frac \\ 0 & 1 \end. \end$$
(3.15)
By comparing (3.8) and (3.14) order by order in \(e^\) we can observe that, in the regime \(\tau \rightarrow i\infty \), \(z=-\tau /2+\phi \), \(\phi \in \mathbb \), where \(Q(\tau )\) is approximated by equation (3.1), the following asymptotic identity holds:
$$\begin&\widetilde_^(z+\tau ) e^ \left( \widetilde_^(z) \right) ^ \nonumber \\&= X_0 \begin1 & \frac (-e^)^e^ \\ 0 & 1\end \begin1 & 0 \\ -\frac (-e^)^ & 1\end X_0^ \nonumber \\&= X_0 \begin1 & \frac (-e^)^e^ e^\\ 0 & 1\end \begin1 & 0 \\ -\frac (-e^)^ e^ & 1\end X_0^\nonumber \\&=\mathbbm +O(e^). \end$$
(3.16)
Therefore,
$$\begin Y_^(z+\tau )\sim M_BY_^(z)e^, \end$$
(3.17)
where
$$\begin M_B&=X_0 \begin \frac & \frac\\ \frac & \frac \end \begin e^ & 0\\ 0 & e^ \end X_0^. \end$$
(3.18)
$$\begin&\mathop ^X_0 \begin \frac & - \frac\\ \frac & \frac \end \begin e^ & 0\\ 0 & e^ \end\nonumber \\ X_0^. \end$$
(3.19)
In conclusion, the asymptotic behaviour of the solution in terms of \(C\) and \(G\) matrices is written as
$$\begin Y_^(z)=C_^A \begin (-e^)^ & 0\\ 0 & (-e^)^ \end G_^A, \end$$
(3.20)
where
$$\begin C_^A&=M_B X_0 \begin e^} & 0\\ 0 & e^} \end,\end$$
(3.21)
$$\begin G_^A&= \begin e^} \frac & 0\\ 0 & e^}\frac \end \begin 1 & \frac\\ 0 & 1 \end. \end$$
(3.22)
Fig. 2
Monodromies and analytic continuations
3. Computation of \(G_^\): As the next step, we compute the asymptotics of \(Y_^(z)\) around \(z=0\). To do this, we first need to perform the analytic continuation to the vicinity of \(z=-\frac\), and then use the formulae [18, eq. (15.10.21)] for the analytic continuation of \(}_2F_1(\cdot , x)\) from \(0+\epsilon \) to \(1-\epsilon \) (see Fig. 2):
$$\begin&}_2F_1(a,b,c,x)=\frac}_2F_1(a,b,1+a+b-c,1-x)+\nonumber \\&\quad + \frac(1-x)^}_2F_1(c-a,c-b,c-a-b+1,1-x),\end$$
(3.23)
$$\begin&}_2F_1(a,b,c,x)=(1-x)^}_2F_1(c-a,c-b,c,x). \end$$
(3.24)
With the above expressions, we obtain that
$$\begin&Y_^(z)=X_0(e^)^ \begin \frac\Gamma (1-2a)\Gamma (-2\,m)} & -\frac\Gamma (1-2a)\Gamma (2\,m)}\\ \\ -\frac\Gamma (2a)\Gamma (-2\,m)} & -\frac \Gamma (2a) \Gamma (2\,m)} \end\nonumber \\&\begin (1-e^)^m & 0\\ 0 & (1-e^)^ \end \nonumber \\ &\times \begin }_2F_1(m,1-2a+m,1+2\,m,1-e^) & -e^}_2F_1(1+m,1-2a+m,1+2\,m,1-e^)\\ }_2F_1(-m,1-2a-m,1-2\,m,1-e^) & e^}_2F_1(1-m,1-2a-m,1-2\,m,1-e^) \end, \end$$
(3.25)
which, in the limit \(z\rightarrow 0\), behaves as
$$\begin&Y_^(z)\sim X_0 \begin \frac\Gamma (1-2a)\Gamma (-2m)} & -\frac\Gamma (1-2a)\Gamma (2m)}\\ -\frac\Gamma (2a)\Gamma (-2m)} & -\frac \Gamma (2a) \Gamma (2m)} \end\nonumber \\&\begin (2\pi i z)^m & 0\\ 0 & (2\pi iz)^ \end \begin 1 & -1\\ 1 & 1 \end. \end$$
(3.26)
The branch of \((2\pi i z)^m\) is chosen by noting that \((1-e^)^m\) is initially defined for \(z=-\frac\), and so, \(\arg (i z)=0\) for \(z=-i0\). The asymptotics at \(z\sim 0\) is written in terms of \(C\) and \(G\) matrices as
$$\begin Y_^(z)\simeq C_0^A \begin (2\pi i z)^m & 0 \\ 0 & (2\pi i z)^ \end G_0^A, \end$$
(3.27)
where
$$\begin C_0^A&= X_0\begin \frac\Gamma (1-2a)\Gamma (-2m)} & -\frac\Gamma (1-2a)\Gamma (2m)}\\ -\frac\Gamma (2a)\Gamma (-2m)} & -\frac \Gamma (2a) \Gamma (2m)} \end \begin e^ & 0\\ 0 & e^ \end,\end$$
(3.28)
$$\begin G_0^A&= \begin e^ & 0\\ 0 & e^ \end \begin 1 & -1\\ 1 & 1 \end. \end$$
(3.29)
\(\square \)
The above information gives us all we need to compute \(\omega _^\). Instead of computing \(\omega _^\) at this point, we will soon see that it will be easier to compute \(\omega _^- \omega _^\) directly.
3.2 Linear Problem of the Trinion from B-Pants DecompositionThe asymptotic analysis for \(\tau \rightarrow 0\) can be inferred by repeating the above computations, constructing the local parametrix by a cut along the B-cycle of the torus. As \(\tau \) is always assumed to lie on the upper half-plane, this limit will be approached along a positive imaginary direction, and sometimes denoted by \(\tau \rightarrow i0\). Consider the linear problem associated to the trinion:
$$\begin \partial _z Y_^(z)=Y_^(z) L_^(z), & L_^(z)=-2\pi i L_^-2\pi i\frac}}, \end$$
(3.30)
where, in analogy with (2.17), the residue matrices are diagonalizable
$$\begin L_^=-(G_^)^ \widetilde\sigma _3\, G_^, & L_0^=(G_0^)^ m\sigma _3 \,G_0^, \end$$
(3.31)
$$\begin L_^ = - L_^- L_^ = (G_^)^ \widetilde \sigma _3 \, G_^. \end$$
(3.32)
We will refer to \((\widetilde,\widetilde)\) as the dual monodromy coordinates, and the precise relation between the dual monodromy data we call \(\left( \widetilde, \widetilde \right) \) and the coordinates \((a, \nu )\) will be derived in the next section. The B-cycle analogue of the one-form (2.21) reads
$$\begin \omega _^&= -\operatorname (-}\sigma _3) \textrmG_^ \left( G_^\right) ^ - \operatorname }\sigma _3 \textrmG_^\left( G_^\right) ^- \operatorname \sigma _3 \textrmG_0^ \left( G_0^\right) ^. \end$$
(3.33)
Using the above relation, we find the following result.
Proposition 3The asymptotics of solution \(Q(\tau )\) in (2.5) for \(\tau \rightarrow +i0\) reads
$$\begin Q(\tau \rightarrow 0)\sim \widetilde-\tau \left( \frac}+ \frac \log \frac)\Gamma (1-2\widetilde-m)})\Gamma (2\widetilde-m)} \right) =\widetilde-\widetilde\,\tau , \end$$
(3.34)
$$\begin e^}\frac)\Gamma (2\widetilde-m)})\Gamma (1-2\widetilde-m)} e^}}. \end$$
(3.35)
ProofLet \(\widetilde-1/\tau \). Together with \(\widetilde(\widetilde)-Q(\tau )/\tau \) this is a symmetry of the isomonodromic equation (2.5) [19]Footnote 4. The asymptotics as \(\widetilde\rightarrow i\infty \) will then have the same form as (3.1), with different parameters:
$$\begin \widetilde(\widetilde) \sim \widetilde\, \widetilde+ \widetilde= -\left( \widetilde-\widetilde\tau \right) /\tau . \end$$
Then noting that \(\widetilde \rightarrow +i\infty \) is equivalent to \(\tau \rightarrow +i0\), and using the relation \(\widetilde=-Q/\tau \), we obtain the result (3.34). \(\square \)
For now (3.35) is simply a definition of \(\widetilde\) in terms of the asymptotics of \(\widetilde\), which will be justified in the following.
As in the previous subsection, we use the behaviour (3.34) to study the behaviour of the Lax matrix \(L_z\) in (2.2), for which, we begin by computing asymptotics of \(x(u,z|\tau )\) around \(\tau \rightarrow +i0\). We start with the following identities of theta function for \(\widetilde= -1/\tau \) [18, 20.7]
$$\begin (- i \tau )^ \theta _1(z\vert \tau ) = -i e^} \theta _1(z\widetilde\vert \widetilde), & (- i \tau )^ \theta _1'(0\vert \tau ) = - i \widetilde\theta _1'(0\vert \widetilde), \end$$
and consequently,
$$\begin x(u,z|\tau )= \widetildee^} x(u\widetilde, z\widetilde|\widetilde). \end$$
(3.36)
Using (3.2), we observe that, in the limit \(\widetilde\rightarrow +i\infty \), the RHS of the above expression behaves as
$$\begin \widetildee^} x(u\widetilde, z\widetilde|\widetilde) \sim 2\pi i \widetildee^}\left( \frac}-1}-\frac}-1} \right) , \end$$
which implies the following behaviour of \(x(u,z\vert \tau )\) for \(\tau \rightarrow +i0\):
$$\begin x(u,z\vert \tau ) \sim \frac e^\left( \frac-1}-\frac-1} \right) . \end$$
(3.37)
Assuming that \(\Re \widetilde>0\), we obtain the following behaviour for the Lax matrix \(L_z\) (2.2) in the limit \(\tau \rightarrow +i0\):
$$\begin L_z(z)\sim \frac\begin -}\,\tau & \frac-}\tau )/\tau }e^}-1} \\ \frac}-}\tau )/\tau }}-1} & }\,\tau \end_^(z). \end$$
(3.38)
The above matrix describes the linear system on a 3-point sphere obtained by cutting the torus along the B-cycle in (3.30). We now compute its diagonalization matrices (3.31) that are needed to compute the one-form \(\omega _^\) (3.33).
Proposition 4The matrices \(G_^, G_^\) are given by
$$\begin G_^B = \begin e^_} & 0\\ 0 & e^_} \end \begin 1 & 0\\ \frac} & 1 \end, & G_0^B&= \begin e^_0} & 0\\ 0 & e^_0} \end \begin 1 & -1\\ 1 & 1 \end, \end$$
(3.39)
$$\begin G_^B = \begin e^/2+i\widetilde_} \frac)\Gamma (2\widetilde-m)})\Gamma (1-2\widetilde-m)} & 0\\ 0 & e^/2-i\widetilde_} \frac)\Gamma (1-2\widetilde-m)})\Gamma (2\widetilde-m)} \end \begin 1 & \quad \frac}\\ 0 & \quad 1 \end, \end$$
(3.40)
which are all determined up to left multiplication by constant diagonal matrices parameterized by \(\widetilde_\), \(\widetilde_0\), and \(\widetilde_\), respectively.
ProofWe compute each of the matrices above.
1. Computation of \(G_^\):
The fundamental solution of the equation (3.30) reads as
$$\begin & Y_^= X_(1-e^)^m \begin (-e^)^}} & 0\\ 0 & (-e^)^}} \end \nonumber \\ & \qquad \times \begin }_2F_1(m,1+m-2\widetilde,1-2\widetilde,e^) & \frac}-1}}_2F_1(1+m,1+m-2\widetilde,2-2\widetilde,e^)\\ \frac} }_2F_1(1+m,m+2\widetilde,1+2\widetilde,e^) & }_2F_1(m,m+2\widetilde,2\widetilde,e^) \end\nonumber \\ & \qquad \times \begin e^-\widetilde\tau )/\tau } & 0 \\ 0 & e^-\widetilde)/\tau } \end\nonumber \\ & \quad Y_^(z)\begin e^-\widetilde\tau )/\tau } & 0 \\ 0 & e^-\widetilde)/\tau } \end. \end$$
(3.41)
Sometimes we prefer to work with solutions for the 3-point problem that do not have twists, in this case we can choose \(Y_^(z)\). This solution contains the matrix \(X_\) which should be chosen in such a way that its monodromies are consistent with monodromies of \(Y_^(z)\) in (3.7). In order to obtain \(G_^\), we begin by computing the B-cycle monodromy:
$$\begin Y_^(z+\tau )=M_BY_^(z)e^, \end$$
(3.42)
and so,
$$\begin M_B=X_ \begin e^} & 0\\ 0 & e^} \end X_^. \end$$
(3.43)
In the limit \(z\rightarrow -i \infty \), the solution (3.41) is given by
$$\begin _^(z)=C_^ \begin (-e^)^} & 0\\ 0 & (-e^)^} \end G_^\begin e^-\widetilde\tau )/\tau } & 0 \\ 0 & e^-\widetilde)/\tau } \end, \end$$
(3.44)
where
$$\begin C_^=X_ \begin e^_} & 0\\ 0 & e^_} \end, & G_^= \begin e^_} & 0\\ 0 & e^_} \end \begin 1 & 0\\ \frac} & 1 \end, \end$$
(3.45)
for an arbitrary parameter \(\widetilde_\).
2. Computation of \(G_^\):
In order to compute \(G_^\), we need to study the behaviour of \(_^\) near \(+i\infty \). This is done by analytic continuation of hypergeometric functions which give us the following expression for \(Y_^\) in (3.41):
$$\begin&_^(z)=X_ (1-e^)^m\nonumber \\&\begin \frac)^2}-m)\Gamma (1-2\widetilde+m)} & \frac-1)\Gamma (1-2\widetilde)\Gamma (2\widetilde-1)}\\ \frac)\Gamma (1+2\widetilde)}\Gamma (1-m)\Gamma (1+m)} & \frac-1)\Gamma (2\widetilde-1)\Gamma (1+2\widetilde)}\Gamma (2\widetilde-m)\Gamma (2\widetilde+m)} \end\nonumber \\&\begin (-e^)^} & 0\\ 0 & (-e^)^} \end\nonumber \\&\times \begin }_2F_1s(m,2\widetilde+m,2\widetilde,e^) & \frac} }_2F_1(1+m,2\widetilde+m,1+2\widetilde,e^)\\ \frac}} }_2F_1(1+m,1-2\widetilde+m,2-2\widetilde) & }_2F_1(m,1-2\widetilde+m,1-2\widetilde,e^) \end. \end$$
(3.46)
We now compute A-cycle monodromy:
$$\begin Y_^(z+1)=M_AY_^(z). \end$$
(3.47)
Plugging in (3.46), up to some infinitely small terms which appear in this approximate computation, we see that
$$\begin M_A=X_ \begin \frac)^2}-m)\Gamma (1-2\widetilde+m)} & \frac-1)\Gamma (1-2\widetilde)\Gamma (2\widetilde-1)}\\ \frac)\Gamma (1+2\widetilde)}\,\Gamma (1-m)\Gamma (1+m)} & \frac-1)\Gamma (2\widetilde-1)\Gamma (1+2\widetilde)}\, \Gamma (2\widetilde-m)\Gamma (2\widetilde+m)} \end \begin e^} & 0\\ 0 & e^} \endX_^. \end$$
(3.48)
Using the definition of \(\widetilde\) (3.35), the above expression can be rewritten as
$$\begin M_A\!\!=\!\! X_\begin \frac-m)}} & -\frac)^2\Gamma (2\widetilde-m)\sin \pi m}-m)} \\ \frac)^2\Gamma (1-2\widetilde-m)\sin \pi m}-m)} & \frac+m)}} \end \begin e^/2} & 0\\ 0 & e^/2} \end X_^. \end$$
(3.49)
As the final step, we note that the asymptotic behaviour of \(Y_^\) in (3.46) for \(z\rightarrow +i\infty \) reads
$$\begin Y_^(z)=C_^ \begin (-e^)^} & 0\\ 0 & (-e^)^} \end G_^\begin e^-\widetilde\tau )/\tau } & 0 \\ 0 & e^-\widetilde\tau )/\tau } \end, \end$$
(3.50)
where, for arbitrary parameter \(\widetilde_\),
$$\begin C_^=M_AX_ \begin e^_} & 0\\ 0 & e^_} \end, \end$$
(3.51)
$$\begin G_^= \begin e^/2+i\widetilde_} \frac)\Gamma (2\widetilde-m)})\Gamma (1-2\widetilde-m)} & 0\\ 0 & e^/2-i\widetilde_} \frac)\Gamma (1-2\widetilde-m)})\Gamma (2\widetilde-m)} \end \begin 1 & \frac}\\ \\ 0 & 1 \end. \end$$
(3.52)
3. Computation of \(G_^\):
The diagonalization matrix \(G_0^\) is obtained by studying the behaviour of the solution (3.41) near \(z=0\), which can be achieved through analytic continuation to \(z=0\). To do this, as in the proof of Proposition 2, we first move from \(z=-\frac\) to \(z=-\frac\), and then perform analytic continuation of the hypergeometric function. We obtain that
$$\begin&_^(z)= X_\begin \frac}\Gamma (1-2\widetilde)\Gamma (-2\,m)}-m)\Gamma (-m)} & -\frac}\Gamma (1-2\widetilde)\Gamma (2\,m)}+m)}\\ -\frac}\Gamma (2\widetilde)\Gamma (-2\,m)}-m)\Gamma (-m)} & -\frac}\Gamma (2\widetilde)\Gamma (2\,m)}+m)} \end (e^)^} \nonumber \\&\begin (1-e^)^m & 0\\ 0 & (1-e^)^ \end\nonumber \\&\times \begin }_2F_1(m,1-2\widetilde+m,1+2\,m,1-e^) & -e^}_2F_1(1+m,1-2\widetilde+m,1+2\,m,1-e^)\\ }_2F_1(-m,1-2\widetilde-m,1-2\,m,1-e^) & e^}_2F_1(1-m,1-2\widetilde-m,1-2\,m,1-e^) \end \nonumber \\&\times \begin e^-\widetilde\tau )/\tau } & 0 \\ 0 & e^-\widetilde\tau )/\tau } \end. \end$$
(3.53)
The above matrix behaves as follows near \(z=0\):
$$\begin Y_^(z)&= X_\begin \frac}\Gamma (1-2\widetilde)\Gamma (-2\,m)}-m)\Gamma (-m)} & -\frac}\Gamma (1-2\widetilde)\Gamma (2\,m)}+m)}\\ -\frac}\Gamma (2\widetilde)\Gamma (-2\,m)}-m)\Gamma (-m)} & -\frac}\Gamma (2\widetilde)\Gamma (2\,m)}+m)} \end\nonumber \\&\begin (-2\pi iz/\tau )^m & 0\\ 0 & (-2\pi iz/\tau )^ \end \begin 1 & -1\\ 1 & 1 \end, \end$$
(3.54)
where \(\arg (-iz/\tau )=0\) for \(z=-0\). Alternatively we can write the above expression as
$$\begin Y_^(z)\!\!=\!\!C_0^ \begin (-2\pi iz/\tau )^m & 0\\ 0 & (-2\pi iz/\tau )^ \end _0^ \begin e^-\widetilde\tau )/\tau } & 0 \\ 0 & e^-\widetilde\tau )/\tau } \end , \end$$
(3.55)
where
$$\begin C_0^B= X_\begin \frac}\Gamma (1-2\widetilde)\Gamma (-2m)}-m)\Gamma (-m)} & -\frac}\Gamma (1-2\widetilde)\Gamma (2m)}+m)}\\ -\frac}\Gamma (2\widetilde)\Gamma (-2m)}-m)\Gamma (-m)} & -\frac}\Gamma (2\widetilde)\Gamma (2m)}+m)} \end \begin e^_0} & 0\\ 0 & e^_0} \end, \end$$
(3.56)
$$\begin G_0^= \begin e^_0} & 0\\ 0 & e^_0} \end \begin 1 & -1\\ 1 & 1 \end, \end$$
(3.57)
for an arbitrary parameter \(\widetilde_\). \(\square \)
Remark 1Expressions for the \(A\)-cycle and \(B\)-cycle parametrices (3.27) and (3.55) do not have branch cuts in the lower-left part of the fundamental domainFootnote 5. This allows us to conclude that for \(\tau \in i \mathbb \), \(\arg (-1/\tau )=i\pi /2\). We can additionally choose \(\arg (\tau )\in (0,\pi )\) everywhere throughout the paper. This gives us the value of the argument of \((-1)\) in the formula (3.55): \(\arg (-1)=+i\pi \).
3.3 Comparison of SolutionsFrom the above subsections, we have two solutions \(Y_^\) (2.16) and \(Y_^\) (3.30) that approximate solution of the same linear problem Y (2.2) in the two different limits \(\tau \rightarrow i \infty \), and \(\tau \rightarrow 0\), respectively. Due to isomonodromy the matrices \(M_A,\,M_B,\,M_0\) are independent of these asymptotic limits, allowing one to relate the monodromy data \((a, \nu )\) to \((\widetilde, \widetilde)\). This leads to the following result.
Proposition 5The formulas (2.16) and (3.30) allow one to express all monodromy data in terms of just \(\widetilde\) and \(\nu \).
$$\begin a&=\frac\log \frac-\pi m/2+\nu /4)\sin (\pi \widetilde+\pi m/2-\nu /4)}-\pi m/2-\nu /4)\sin (\pi \widetilde+\pi m/2+\nu /4)},\end$$
(3.58)
$$\begin \widetilde&=4\pi a-2i \log \frac-\pi m/2-\nu /4)}+\pi m/2-\nu /4)}. \end$$
(3.59)
ProofIn order to obtain the precise map between the data \((a, \nu )\) and \((\widetilde, \widetilde)\), respectively, it is sufficient to compare the traces of monodromies. Comparing (3.10), (3.48), we get
$$\begin \operatorname M_A=e^+e^=e^/2}\frac-m)}}+e^/2}\frac+m)}}. \end$$
(3.60)
Similarly, from (3.19), (3.43) one obtains the equality
$$\begin \operatorname M_B=e^\frac+e^\frac=e^}+e^}. \end$$
(3.61)
Using the same expressions as above, we further obtain that
$$\begin \operatorname M_AM_B&=e^\frac+e^\frac\nonumber \\&=e^/2-2\pi i\widetilde}\frac-m)}}+e^/2+2\pi i\widetilde}\frac+m)}}. \end$$
(3.62)
Let us now analyse the expressions above. From (3.61) one can get the expression for a in terms of \(\widetilde\), \(\nu \):
$$\begin (e^-1)(e^}+e^})=e^(e^-e^)+e^(e^-e^), \end$$
(3.63)
and therefore we get (3.58)
$$\begin e^=\frac}+e^}-e^-e^}}+e^}-e^-e^}. \end$$
(3.64)
The variable \(\widetilde\) can be expressed in terms of a, \(\widetilde\), \(\nu \) by considering the following combination:
$$\begin&\operatorname M_A-e^}\operatorname M_AM_B \nonumber \\&\!=\! e^\!+\!e^-e^}\nonumber \\&\quad \left( e^\frac+e^\frac\right) \nonumber \\&=(1-e^})e^/2}\frac+m)}}. \end$$
(3.65)
Comparing the LHS and RHS of the equation above, we get:
$$\begin&e^/2}=\frac}\left( e^\sin \pi (2a-m) + e^\sin \pi (2a+m) \right) }+m)} \nonumber \\&=e^\frac}\left( e^\sin \pi (2a-m) + e^\sin \pi (2a+m) \right) }) \sin 2\pi a\sin \pi (2\widetilde+m)}. \end$$
(3.66)
Substituting (3.58) in the above expression and simplifying it, we get (3.59). \(\square \)
One can obtain an analogous result to Proposition 5 for the pair of variables \(\widetilde\), \(\nu \):
$$\begin \begin \widetilde&=\frac\log \frac/4)\sin (\pi a+\pi m/2-\widetilde/4)}/4)\sin (\pi a+\pi m/2+\widetilde/4)},\\ \nu&=4\pi \widetilde-2i\log \frac/4)}/4)}. \end \end$$
(3.67)
We can obtain further constraint on the monodromy data as follows: since there is overall \(SL(2)\) action on the \(C\) matrices, without loss of generality, one can choose \(C_0^=C^_0=1\). This in turn implies that
$$\begin X_0\mathop ^ \begin e^ & 0\\ 0 & e^ \end^ \begin \frac\Gamma (1-2a)\Gamma (-2m)} & -\frac\Gamma (1-2a)\Gamma (2m)}\\ -\frac\Gamma (2a)\Gamma (-2m)} & -\frac \Gamma (2a) \Gamma (2m)} \end^ \end$$
(3.68)
and
$$\begin X_\mathop ^ \begin e^_0} & 0\\ 0 & e^_0} \end^ \begin \frac}\Gamma (1-2\widetilde)\Gamma (-2m)}-m)\Gamma (-m)} & -\frac}\Gamma (1-2\widetilde)\Gamma (2m)}+m)}\\ -\frac}\Gamma (2\widetilde)\Gamma (-2m)}-m)\Gamma (-m)} & -\frac}\Gamma (2\widetilde)\Gamma (2m)}+m)} \end^. \end$$
(3.69)
Remark 2The coordinates \(\operatorname M_A\), \(\operatorname M_B\) and \(\operatorname M_AM_B\) satisfy the character variety relation (see [20] for example).
$$\begin \operatorname M_0=(\operatorname M_B)^2-(\operatorname M_A)(\operatorname M_B)(\operatorname M_AM_B)+(\operatorname M_AM_B)^2+(\operatorname M_A)^2-2 \end$$
(3.70)
which is known as the Fricke cubic. Performing the transformation twice does not give the original coordinates, i.e. \(\left( \widetilde},\widetilde}\right) \ne \left( a,\nu \right) \). This is because, while (3.60) and (3.61) are invariant under this operation, (3.62) is not. Instead, doing the transformation twice exchanges the two roots of (3.70) seen as a quadratic equation for \(\operatorname M_AM_B\), namely
$$\begin \operatorname M_AM_B\mapsto \operatorname M_A\operatorname M_B-\operatorname M_AM_B. \end$$
(3.71)
We can notice that
$$\begin&\operatorname M_A\operatorname M_B-\operatorname M_AM_B\nonumber \\&=e^\frac+e^\frac=\nonumber \\&=e^/2+2\pi i\widetilde}\frac-m)}}+e^/2-2\pi i\widetilde}\frac+m)}}. \end$$
(3.72)
Therefore, if we fix the values of \(a\) and \(\widetilde\), this involution acts by
$$\begin \nu \mapsto -\nu ,\qquad \widetilde\mapsto -\widetilde, \qquad m\mapsto -m. \end$$
(3.73)
We can further choose the following expressions for \(\delta _0\), \(\widetilde_0\) so as to simplify the expressions of \(M_A\), \(M_B\):
$$\begin \delta _0=\Delta _0-\frac \log \frac\Gamma (2a+m)\Gamma (1/2-m)}, \end$$
(3.74)
and
$$\begin \widetilde_0=\widetilde_0-\frac\log \frac\Gamma (1-2\widetilde+m)\Gamma (1/2-m)}-m)\Gamma (1/2+m)}. \end$$
(3.75)
Finally, comparing the off-diagonal elements of monodromy matrices (3.48) and (3.19), we get
$$\begin \Delta _0-\widetilde_0=\frac\log \frac\sin \pi (2\widetilde-m)}\cos 2\pi \widetilde}. \end$$
(3.76)
Remark 3(Redundancies in monodromy coordinates) The variables \((a,\,\nu ,\,m)\) are not actual coordinates on the character variety, since certain discrete transformations are mapped to the same point in monodromy space. We list them here:
1.The transformation \(m\mapsto -m\) is a symmetry of the original problem, but to preserve monodromy data we should also transform \(\nu \) and \(\widetilde\):
$$\begin m\mapsto -m,\qquad \nu \mapsto \nu +2i\log \frac,\qquad \widetilde\mapsto \widetilde+2i\log \frac+m)}-m)}; \end$$
(3.77)
2.Coordinates of opposite sign describe the same point in the character variety:
$$\begin \nu \mapsto -\nu ,\qquad a\mapsto -a \end$$
(3.78)
and
$$\begin \widetilde\mapsto -\widetilde,\qquad \widetilde\mapsto -\widetilde; \end$$
(3.79)
3.We also have the four trivial transformations that can be applied independently, signalling the fact that the monodromies only depend on exponentiated variables:
$$\begin a\mapsto a+k_a, \,\, \widetilde\mapsto \widetilde+k_},\,\, \nu \mapsto \nu +4\pi k_,\,\, \widetilde\mapsto \widetilde+4\pi k_},\,\, m\mapsto m+k_m,\,\, k_\in \mathbb . \end$$
(3.80)
Summarising this we notice that monodromy manifold is not \(\mathbb ^3\) with coordinates \(m,a,\,\nu \) or \(m,\,\widetilde,\,\widetilde\), but instead
$$\begin \mathbb ^3/\\simeq \mathbb ^3/\. \end$$
(3.81)
The tau function is a function on \(\mathbb ^3_\), but it does not descend to a function on the quotient. Rather, it is a section of a line bundle on the quotient.
Comments (0)